Orders are up, the sales team is pleased, and the supplier payment is due. Yet the bank balance feels tighter than last month.
If customers are buying on credit, more invoiced sales can mean more money waiting to be collected. The business may be growing and still have less room to place the next order. Start by separating sales, outstanding invoices and amounts already overdue.
Which invoices actually need action?
An invoice that is not yet due is outstanding but not overdue. An invoice past its agreed due date needs a different conversation. Treating them alike can waste follow-up effort and strain a good customer relationship.
Group the balance by customer and due date. Then examine disputes, missing documents, unallocated payments and genuine late payment. Each needs a different next step.
For example, a customer who has paid but whose receipt is not matched does not need another payment demand. They need the records corrected.
Turn the ageing report into an action queue
Use invoice due dates to distinguish overdue debt from invoices still within terms. Record customer, invoice reference, unpaid amount, due date, evidence, owner and next action. Then route the issue rather than sending everyone the same reminder.
Overdue and undisputed
A ₹1 lakh invoice is seven days past due and the customer accepts the amount. Collections owns the follow-up: confirm the payment date, record the commitment and review it when that date arrives. If it is missed, escalate under the agreed credit policy.
Disputed or missing documents
A ₹60,000 invoice is overdue because the customer needs delivery evidence or disputes the quantity. Operations supplies the document or investigates the difference; finance agrees the resulting balance. Collections follows the confirmed amount. Repeating a payment demand will not supply the missing evidence.
Payment received but unmatched
A ₹40,000 bank receipt is visible, but its invoice allocation is missing. Finance verifies the payer and reference, then matches it to the correct balance. This corrects the outstanding record; it does not collect another ₹40,000 of cash.
Not yet due
Keep these invoices visible for planning, but separate from the overdue action queue. Use the agreed payment terms, not invoice age alone, to decide whether a payment is late.
How much buying room is waiting in collections?
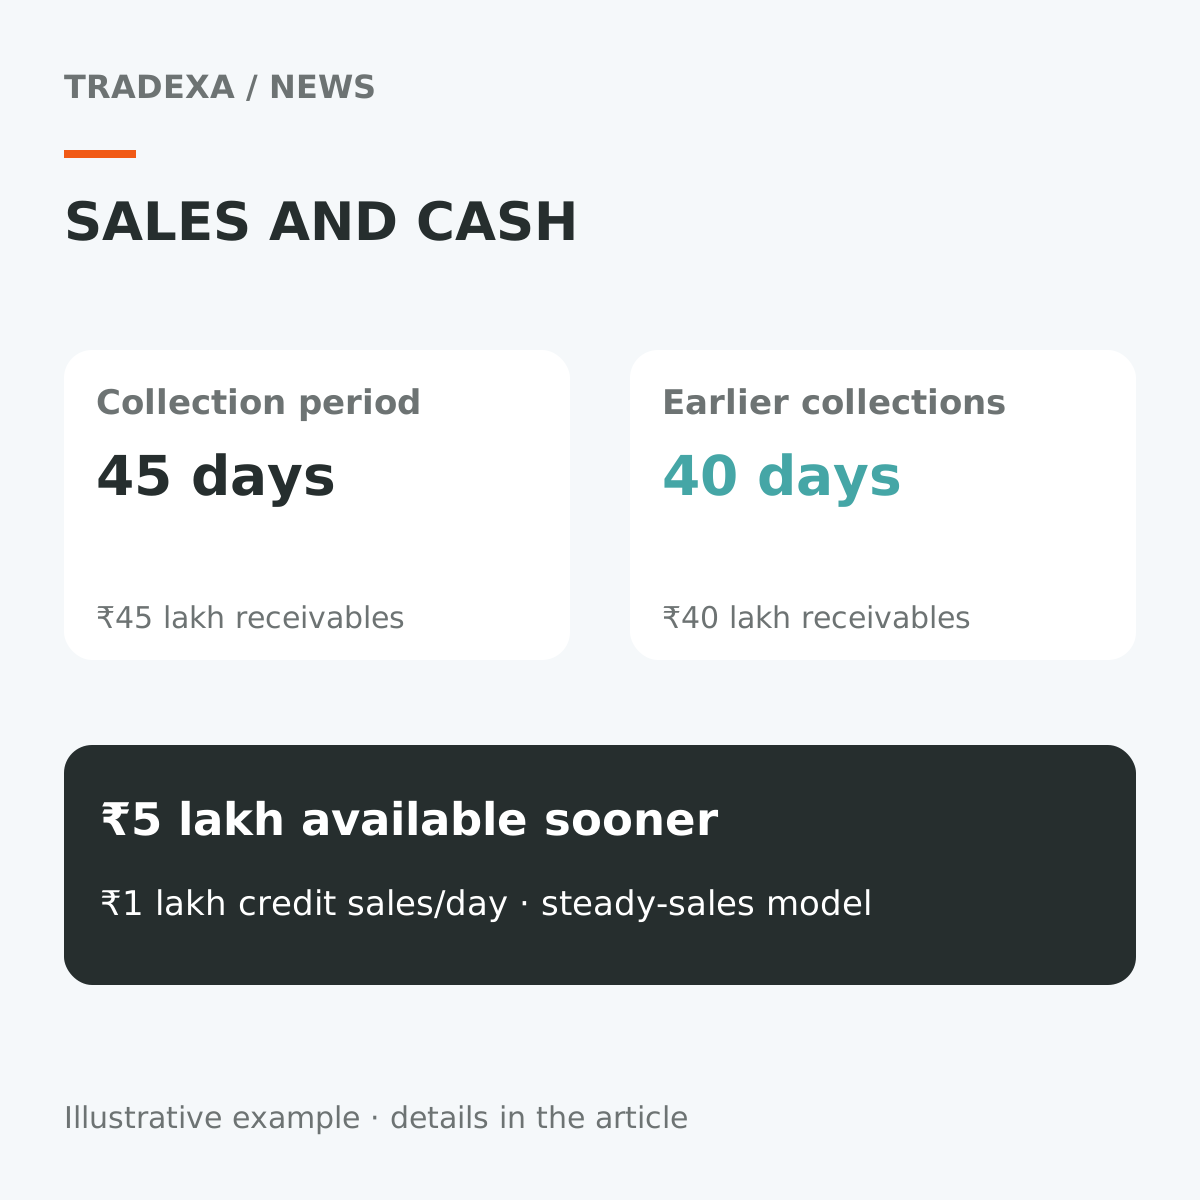
Take an illustrative business making ₹30 lakh of credit sales in a 30-day month: roughly ₹1 lakh a day. If collections currently average 45 days, a simple steady-sales model implies ₹45 lakh tied up in receivables.
Reducing that average to 40 days could bring the balance to ₹40 lakh, releasing ₹5 lakh once the lower collection period is sustained. This assumes steady sales and broadly similar payment patterns; it is not a forecast for a seasonal business.
The five-day change is a target to test, not a number created by the report. Track time lost waiting for documents separately from customer payment delays. Resolving document holds and following agreed payment dates can bring cash forward; matching an already received payment improves the record but is not new cash. Compare actual collection timing over several comparable periods before using 40 days in a buying plan.
₹5 lakh collected sooner is not ₹5 lakh extra profit. It is money available earlier for supplier payments or other business needs. At an illustrative 12% annual financing rate, a sustained ₹5 lakh lower borrowing requirement would reduce financing cost by ₹60,000 a year. Actual borrowing terms and timing determine whether that saving exists.
Will the next order deepen the problem?
Before extending more credit, look at the customer's existing balance, due invoices and unresolved disputes. A large order is not necessarily attractive if it increases an already difficult exposure.
HyperInventory supports credit limits in configured order and invoice workflows, along with aged-receivables visibility. Confirm the exact enforcement points in your setup; do not assume every sales channel applies an identical block.
A limit is not a replacement for a commercial decision. Someone still needs responsibility for exceptions, terms and collection follow-up.
Make follow-up easier to act on
Give the person contacting a customer a usable record: invoice, amount, due date, related documents and any payment already received. Agree a next date or action rather than repeatedly sending the same reminder.
Tradexa's reporting and supported accounting connections can help bring the operational and finance records into a clearer workflow. Your finance team still needs to reconcile them and decide how balances should be treated.
The growth benefit is choosing which business you can fund. Earlier collections can pay for replenishment of products with confirmed demand instead of leaving good orders waiting for buying cash. Keep that purchase decision separate from the collection target: use the stock buying review to decide where the money should go.
Example note: The numbers illustrate a scenario, not measured customer results. Actual outcomes vary with business type, category, demand, competition, team, processes, business setup, external conditions and how effectively the workflow is used. Replace the example inputs with your own before making a decision.